
Bank Statement Loans
Built for: self-employed and 1099 borrowers whose tax returns don't show their real income.
Read More
Houston-Based Mortgage Broker & Lender
Top Rated Loan Advisors Across Texas
Built for: self-employed and 1099 borrowers whose tax returns don't show their real income.
Read MoreBuilt for: buyers with stronger credit who want fewer overlays and no upfront mortgage insurance.
Read MoreBuilt for: buyers who can afford the monthly payment but not the down payment and closing costs.
Read MoreBuilt for: investors qualifying on a property's rental income instead of their personal income.
Read MoreBuilt for: first-time buyers with a limited down payment or credit that is still rebuilding.
Read MoreBuilt for: borrowers who file taxes with an ITIN instead of a Social Security number.
Read More
Loan Quiz
Take this quick quiz to point you in the right direction.
5 questions · 30s
Pick an answer to begin →
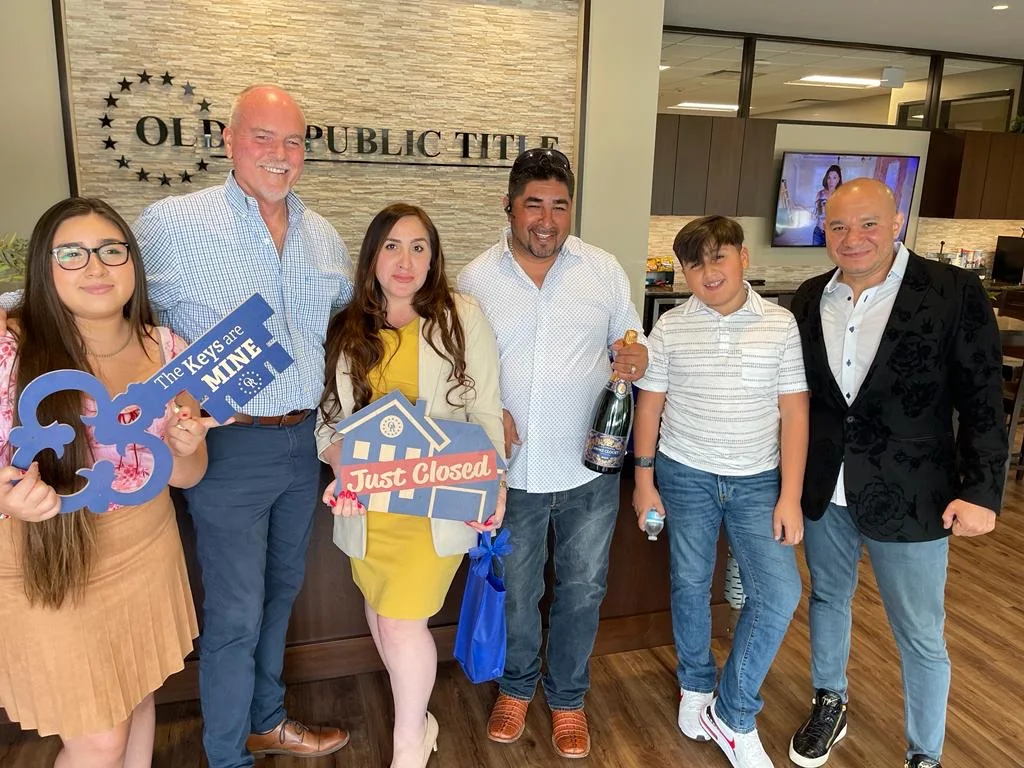
About Entrust Home Lending
Seasoned Loan Officers
Award-recognized officers who get self-employed, ITIN, and foreign national files to the finish line.
Fast Loan Decisions
Underwriting in-house means quick decisions, even on bank statement, DSCR, and hard money loans.
Clear Communication
Straight answers and milestone updates the whole way, in English or Spanish.
A Smooth Process
Stress-free from application to closing, whether it's your first home or your fifth rental.
One Team, Not a Call Center
The same people from pre-approval to keys, not a rotating queue.
How It Works
01
See what your dream home could look like. Run the numbers yourself with our calculators.
Try the Calculators →02
Contact a loan officer and get pre-approved to take the first big step.
Get Pre-Approved →03
A loan officer reviews your file personally and tells you what you qualify for, and what to fix if you don't yet.
04
We handle documentation, appraisal, and underwriting in-house and keep you updated at every step.
05
Clear to close, sign, and get your keys — with milestone updates the whole way.
Headquartered in Houston, lending across Harris County and the rest of Texas.
No — that's the most common myth in the process. FHA financing starts at 3.5% down, conventional financing can go as low as 3% for buyers who qualify, and VA and USDA loans can require nothing down for eligible borrowers. Texas down payment assistance programs (TDHCA and TSAHC) can reduce the cash needed at closing further. The right number depends on the program and the situation, not a single figure that applies to everyone.
No. It depends on the program: FHA financing allows scores as low as 500 with a larger down payment, or 580 with the standard 3.5% down. Conventional loans typically want 620 or above. Non-QM and bank statement programs set their own guidelines and work with a wider range of credit histories. A loan officer can tell you where a specific score actually lands across programs.
Pre-qualification is a quick, informal read on what you might afford based on what you report — useful for planning, not for making an offer. Pre-approval means a loan officer has actually reviewed documentation (income, assets, credit) and can give you a real number a seller will take seriously.
A bank can only offer its own loan products. A broker works with multiple loan programs and matches a borrower's actual situation to whichever one fits — which matters most for buyers who don't fit a standard conventional box. Entrust also underwrites in-house rather than routing files through outside processing, so a loan officer can tell you directly what a file needs.
Yes to both, through programs built for exactly those situations. Bank statement loans use 12–24 months of actual bank deposits instead of tax returns, which suits self-employed borrowers and 1099 contractors whose returns don't reflect their real cash flow. ITIN loans are for borrowers who file taxes with an Individual Taxpayer Identification Number instead of a Social Security number — an established path, not a workaround, and one Entrust's bilingual team works with often.
Call, or send a message and a loan officer follows up directly.
(346) 730-1153Prefer not to fill out a form? Call (346) 730-1153 or request a rate.
Serving Texas and more for over 20 years
Chat isn't available right now — here are the fastest ways to reach us.


